
EQUITY RESEARCH
Acba Bank OJSC (AMX: ACBA) | Update Q2 2026
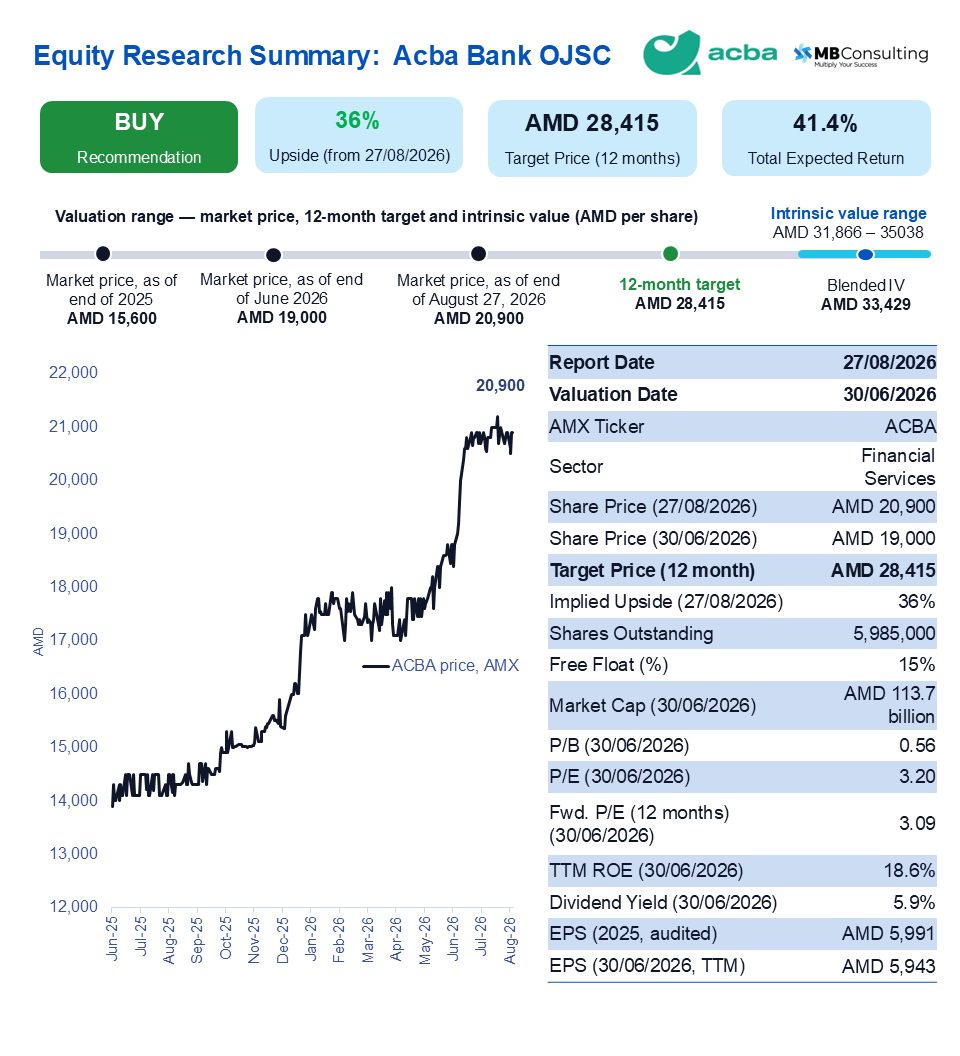
Valuation date: 30 June 2026 Report date: 27 August 2026 Expected total return: 41.4%
Investment thesis
RecommendationBUY
Rating scale: Buy >+15% | Hold −10% to +15% | Sell <−10% expected total return over a 12-month horizon.
12-month target
AMD 28 415
Price (August 27, 2026)
AMD 20 900
Upside to target
+36%
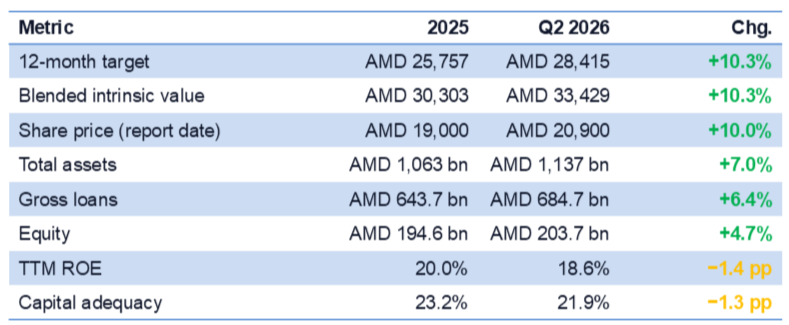
We reiterate our Buy rating and raise our 12-month target to AMD 28 415, up 10.3% from AMD 25 757 at initiation. Blended intrinsic value rises to AMD 33 429 (from AMD 30 303) on a higher equity base and continued earnings growth. The shares have risen 34% from our end-2025 valuation date to AMD 20 900, the re-rating we anticipated is underway, yet still trade at a 37.5% discount to intrinsic value.
Growth continued into H1 2026, with assets up 7% and gross loans up 6.4% since year-end. TTM ROE moderated to 18.6%, moving toward the bank's normalized long-term return profile, while continued balance-sheet expansion drew down the capital buffer.
Changes since last update (December 2025)
ISSUER-PAID RESEARCH
This note was prepared under an issuer-paid arrangement with Acba Bank OJSC for a fixed fee that is independent of its conclusions, the rating assigned, and the target price. MB Consulting retains full editorial control over methodology, assumptions, and conclusions. Full disclosures, including relationship and personal holding disclosures, appear at the end of Equity Research Note downloadable from this page.
VALUATION METHODOLOGY
Fair value is derived from three independent methods applied to the consolidated group: free cash flow to equity, justified price-to-book, and an excess return model. Each is equally weighted. The 12-month target price applies a 15% convergence discount to blended fair value, reflecting expected partial rather than full closure of the discount over the horizon. Key assumptions are disclosed in the valuation section above.